Draw it, repay it, draw again
Take what is needed at closing and draw again as the balance is paid down, without a second application.
This takes a few seconds. Please don’t close this page — we’ll take you straight to your secure application when it’s ready.
Badger Business places home equity lines with lenders that underwrite and fund them online. The application asks for the three things that size a line: the property, what is already owed against it, and the income behind it. Checking your rate is a soft credit pull and does not affect your score.
A home equity line is sized against the property and what is already owed on it. These are the answers that set the limit.
A primary residence carries the largest line and the longest terms.
A home held in your name, jointly, in a revocable trust or by an LLC all qualify.
A second mortgage or an existing home equity line counts against the same 80%. Enter 0 if the first mortgage is the only loan on the home.
This is what the soft credit pull runs on. It does not affect your credit score, and we already have your name and how to reach you.
Used for the soft pull only. Nothing here is a hard inquiry.
The mortgage statement and the insurance page are what confirm the loans already on the property. Income is what sizes the line against them.
Attach what you have. Nothing here holds up your rate. The rest can go up later in your secure application.
A property tax bill, an HOA statement, a recent appraisal, a payoff letter on the loan being consolidated, and anything else already in hand. No limit on how many.
PDF, JPG, PNG, Excel or Word, up to 100 MB per file. Identity verification and the online signing happen later, in the secure application.
Check the numbers on the home. You can go back and change anything.
Your file is going out to the lenders now. This takes about a minute, and the offers land in your portal as they come back.
A home equity line is applied for, signed and funded online, and it stays open as you repay it, so the equity is there for the next thing as well as this one.
Take what is needed at closing and draw again as the balance is paid down, without a second application.
The application uses a soft credit pull, so the line and the rate are known before any hard inquiry.
Owners use a home equity line to buy a business, fund equipment or pay down higher-rate debt.
Badger Business stays on the file through closing, and the portal shows where it stands at each stage.
The home, what is owed on it and your income, in one application with no fee.
A soft credit pull returns the limit, the rate and the term options without a mark on your credit.
The mortgage statement, the insurance page and proof of income go up once, into one repository.
The lender prepares the closing documents and explains how signing works in the state.
Funds are available after closing, and the rest of the line stays open.
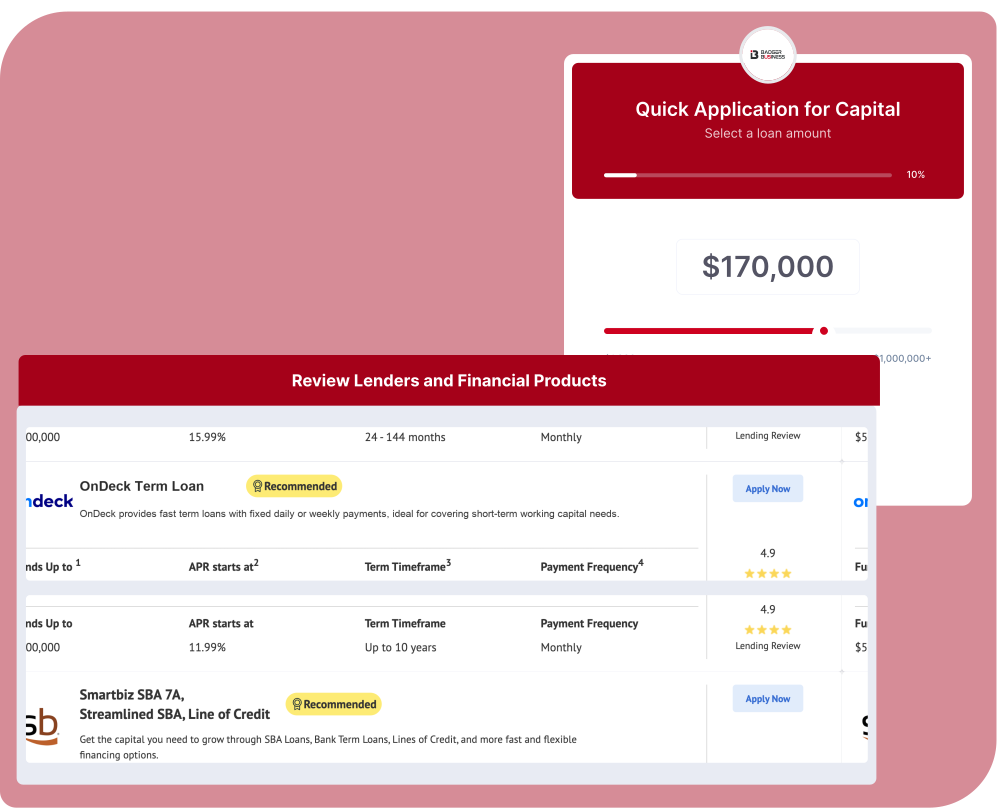
What these programs allow, and where a home equity request usually lands.
The limit is the value of the home at 80%, less the mortgage and anything else already secured by it.
A longer term lowers the payment on the same draw. The term is chosen at closing and applies to the balance.
In your name, jointly, in a revocable trust or by an LLC, on a primary residence, a second home or investment property.
Answer what the program asks, and the line, the rate and the term come back in the portal. Checking does not affect your credit score.
Rather talk it through first?